Market reach analysis · Report of 09 November 2026
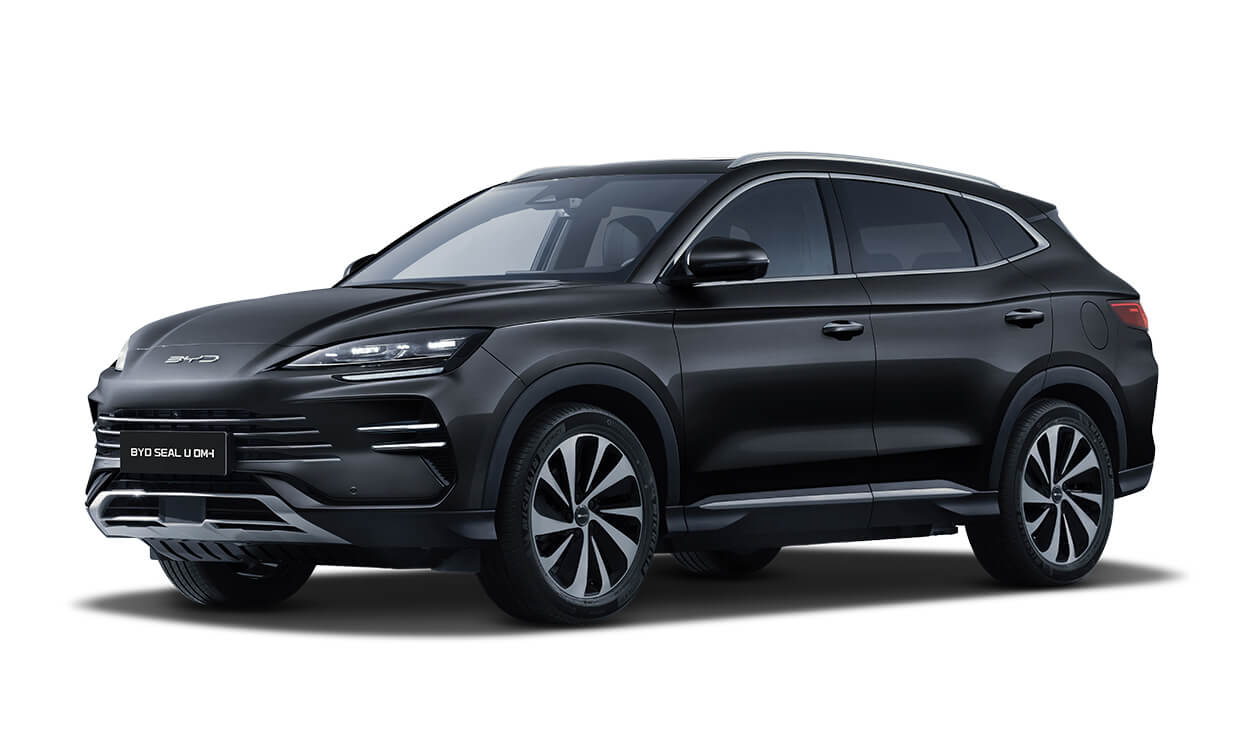
BYD SEAL U DM-i
Western Europe Market Reach Analysis
The fastest-growing plug-in hybrid launched in Western Europe in the last five years — and a case study in how price advantage, product fit and unresolved hardware and service gaps interact when a new entrant scales.
Six numbers that carry the executive signal
Six indicators carry most of the executive signal in the report. Each is reproduced as stated, with its own base — the report publishes no composite sentiment, attention or momentum score.
No composite sentiment or attention index exists in the source report; each figure above is reproduced exactly as stated, with its own denominator. Where the report gives no base, the figure is directional only.
What the growth means, and what limits it
Six findings that explain why the model grew, where the growth is fragile, and what constrains the next phase. Evidence lines quote the report; implications are the reading this site adds for account and strategy teams.
A three-phase trajectory runs from low organic visibility to stabilised high visibility. Registrations reach 63,186 in Jan–Nov 2026, the model is No. 1 in the UK and No. 2 in Spain, and delivery lead times lengthened from 3 months to 5–6 months by mid-2026.
Satisfaction splits cleanly by usage profile: 82% home-charging city commuter, 77% family weekly charger, 56% frequent motorway driver, 41% without home charging access.
A consistent 15–20% gap below established competitors is named the single largest adoption driver, while 78% of sales sit in the base Boost trim.
In the maturation phase, discussion shifted to regulatory and supply-chain risk. Regulatory and trade policy is 21% of discussion themes, and EU tariff announcements became the single largest topic in Q3–Q4 2026.
The 2.3 kW onboard AC charger is the most criticised hardware feature against a 7 kW European norm; 19% of early adopters report ADAS false braking; dealer density is 1 per 1.2 million inhabitants against 1 per 75,000 for Volkswagen.
Fleet share is below 15% although company-car drivers represent 62% of Western European PHEV sales; France, Benelux and Scandinavia sit below 3% PHEV share against 11% in the UK and Spain.
Four levers, four barriers
Four opportunities are quantified in the source report. Values marked as projections are the report's own projections, not observed outcomes.
Fleet share is currently below 15% despite full eligibility for maximum corporate tax benefits, while company-car drivers represent 62% of total Western European PHEV sales.
Extremely low resale liquidity is suppressing new-buyer confidence. A certified used vehicle programme is projected to increase new sales by 9% within 12 months.
The model holds below 3% PHEV market share in France, Benelux and Scandinavia, compared with 11% in the UK and Spain.
78% of sales are for the base Boost trim, indicating significant unexploited margin opportunity.
Adoption barriers
Reported by 19% of early adopters and the single largest source of negative owner feedback. A software fix is available but not yet fully rolled out.
Out of alignment with European market expectations, where 7 kW is considered the PHEV standard, and the most frequently criticised hardware feature.
Average dealer density is 1 per 1.2 million inhabitants, compared with 1 per 75,000 for Volkswagen.
Soft tuning optimised for urban use fails European highway driving expectations; owners and reviewers describe the body as floaty.
Five sequenced priorities with named KPIs
Five sequenced actions from the source report, with the report's own expected outcomes, timelines and success metrics.
| Priority | Action | Expected outcome | Timeline | Success KPI |
|---|---|---|---|---|
| 1 | Complete full rollout of v1.3.0 ADAS software update | 45% reduction in negative review sentiment | December 2026 | ADAS complaint rate <5% |
| 2 | Upgrade onboard AC charger to 7 kW for 2027 model year | Eliminate largest hardware criticism | Q1 2027 | Charging satisfaction >70% |
| 3 | Launch certified used vehicle programme in the UK | Improved residual values and buyer confidence | Q2 2027 | 12 month residual value >70% |
| 4 | Accelerate dealer network expansion | Reduce service related complaints | End 2027 | Dealer density 1 per 500,000 inhabitants |
| 5 | Recalibrate suspension tuning for European road conditions | Improve media review scores by 1.2/10 | 2027 facelift | Ride quality complaint rate <15% |
Success metrics are the report's targets, not verified results. Priorities reflect the report's ordering, not a modelled impact ranking.
Priority 1–2 are product fixes with named dates; priority 3–5 are capability builds that depend on partners, homologation and model-year timing. Commitments made to customers should track the fix calendar rather than campaign timing.
Every section, table and reference
The complete report is available section by section, with all nine source tables, all four source figures and all fourteen references.
Custom research
Need this analysis for a specific account or market?
This site is one report in a planned Western Europe automotive intelligence library. The three entry points below are reserved for commercial enquiries; they are configured by the publishing team and are intentionally blank in this build.
Placeholder state by design: no email address, owner or submission endpoint is invented. Configure CONFIG.contact in src/content_core.py before any external release.